Market overview and structural significance of the Direct Selling Market
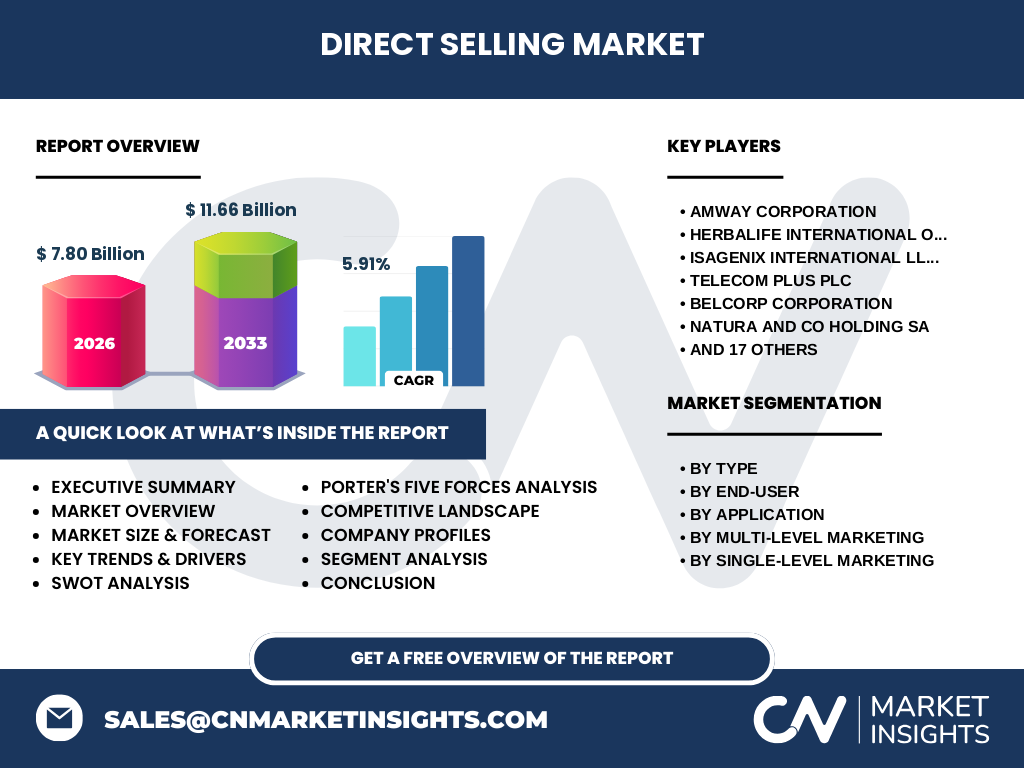
Our analysis indicates that the Direct Selling Market market size reaches 7.80 Billion in 2026. This dynamic industry bypasses traditional brick-and-mortar retail through person-to-person commerce, heavily utilizing independent consultants to distribute wellness and cosmetic goods globally while navigating complex regulatory frameworks enforced by bodies like the Federal Trade Commission.
Structural Growth Drivers and Restraints in the Industry
Based on our research, the Direct Selling Market industry trends are heavily fueled by rising consumer demand for personalized entrepreneurship and nutritional supplements. However, supply chain constraints involving raw material procurement for botanical extracts and strict compliance mandates by the Direct Selling Association continue to restrain rapid geographic expansion.
Emerging Trends Shaping the Sector
The data suggests a decisive pivot toward digital social selling and hybrid compensation plans. Enterprises like Amway Corporation and Herbalife International of America Inc. are leveraging proprietary mobile applications to streamline customer acquisition, bypassing legacy door-to-door methodologies in favor of targeted social media engagement.
How did the COVID-19 pandemic alter the trajectory of the Direct Selling Market?
The pandemic catalyzed an accelerated digital transformation across the ecosystem. While traditional party plan systems faced severe logistical bottlenecks, home-bound consumers increased spending on wellness items from USANA Health Science Inc. and Juice Plus+ Company LLC, permanently shifting the sector toward digital-first operational models.
Competitive Benchmarking and Market Concentration
Our analysis reveals a moderately consolidated competitive landscape where established giants like Natura and Co Holding SA and Avon Products Inc. command substantial share. Industry leaders leverage extensive global distributor networks, forcing regional competitors to innovate with localized product formulations and specialized binary compensation structures.
Executive Summary: Key Findings
The Direct Selling Market analysis projects robust expansion to 11.66 Billion by 2033, driven by a steady 5.91% CAGR from 2027 to 2027. Strategic agility, technological adoption in e-commerce, and heavy investment in wellness portfolios remain the primary determinants of long-term corporate profitability.
Market Forecast and Valuation Trajectory (2027 to 2033)
Driven by compounding consumer adoption and digital distributor onboarding, the market is set to expand from 7.80 Billion in 2026 to reach 11.66 Billion by 2033. This consistent 5.91% CAGR reflects sustained demand across emerging economies and continuous portfolio diversification by key multinational direct sellers.
Segmentation Analysis Across Product Lines and Channels
Our comprehensive breakdown categorizes the market by Single-Level Marketing and Multi-Level Marketing, alongside end-user dynamics spanning individual and commercial clients. Application sectors are heavily anchored by wellness and cosmetics, while distribution relies on binary, unilevel, and matrix compensation frameworks deployed by firms like Primerica Inc.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America and Asia-Pacific leading revenue generation due to high smartphone penetration and mature independent contractor networks. Conversely, Latin American markets, supported by players like Belcorp Corporation, demonstrate rapid volume growth despite localized currency volatility and inflationary pressures.
In-Depth Regional Review of Growth Hotspots
Asia-Pacific represents the most aggressive growth frontier, bolstered by rising disposable incomes and robust acceptance of social selling. Regulatory adaptations by local trade ministries in key economies have fostered stable operating environments for major regional innovators like Atomy Co Ltd. and DXN Holdings Bhd.
Strategic Positioning of Leading Company Profiles
Market leaders utilize distinct competitive strategies. Nu Skin Enterprises Inc. and Oriflame Cosmetics S.A. focus on anti-aging skin care innovations, while Medifast Inc. captures high-margin weight management segments through structured dietary programs, aligning distributor incentives with long-term customer retention metrics.
Porter's Five Forces Assessment of Competitive Intensity
The threat of new entrants remains moderate due to steep regulatory compliance hurdles and brand loyalty requirements. Meanwhile, buyer power is counterbalanced by proprietary product formulations from firms like Isagenix International LLC and Forever Living Products International Inc., which reduce direct substitution risks.
SWOT Analysis of the Direct Selling Ecosystem
Key strengths lie in low overhead distributor networks and high customer lifetime value. However, high consultant churn remains a persistent weakness. Opportunities abound in digital cross-border expansion, while regulatory scrutiny from consumer protection watchdogs poses a continuous strategic threat.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with certified raw material sourcing for botanicals and chemicals, progressing through contract manufacturing and warehousing at major logistics hubs. Independent distributors act as the critical final link, utilizing digital marketing to deliver goods directly to commercial and individual end-users.
Investment Insights and High-Potential Areas
Strategic capital should target technology platforms enhancing distributor onboarding and mobile checkout experiences. Companies integrating hybrid compensation models with scientifically validated wellness portfolios, such as PM International AG, present the most compelling risk-adjusted investment opportunities.
Conclusion and Strategic Takeaways for Stakeholders
Sustained success in the Direct Selling Market requires aggressive technological modernization and strict adherence to evolving global regulatory standards. Organizations that successfully merge social commerce tools with high-retention product categories will outperform broader retail benchmarks through 2033.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by synthesizing direct trade registry disclosures, primary executive interviews with industry stakeholders, and secondary macroeconomic indicators from global commerce associations. This multi-layered approach ensures precise market sizing and reliable long-term forecasting models.
Scope of the Report and Operational Limitations
This report covers global direct selling activities across single-level and multi-level structures, evaluating wellness, cosmetics, and household goods segments. Limitations include potential reporting discrepancies in private entity financials and unpredictable shifts in regional trade policies affecting cross-border distributor payouts.
Recent Developments: Corporate Announcements and Strategic Moves
Recent industry momentum features aggressive product rollouts and technological partnerships. Notable moves include eXp World Holdings Inc. expanding its cloud-based brokerage model, and companies like Scentsy GB PTY Ltd. and Vorwerk Deutschland Stiftung and Co KG enhancing supply chain automation to mitigate international freight bottlenecks.